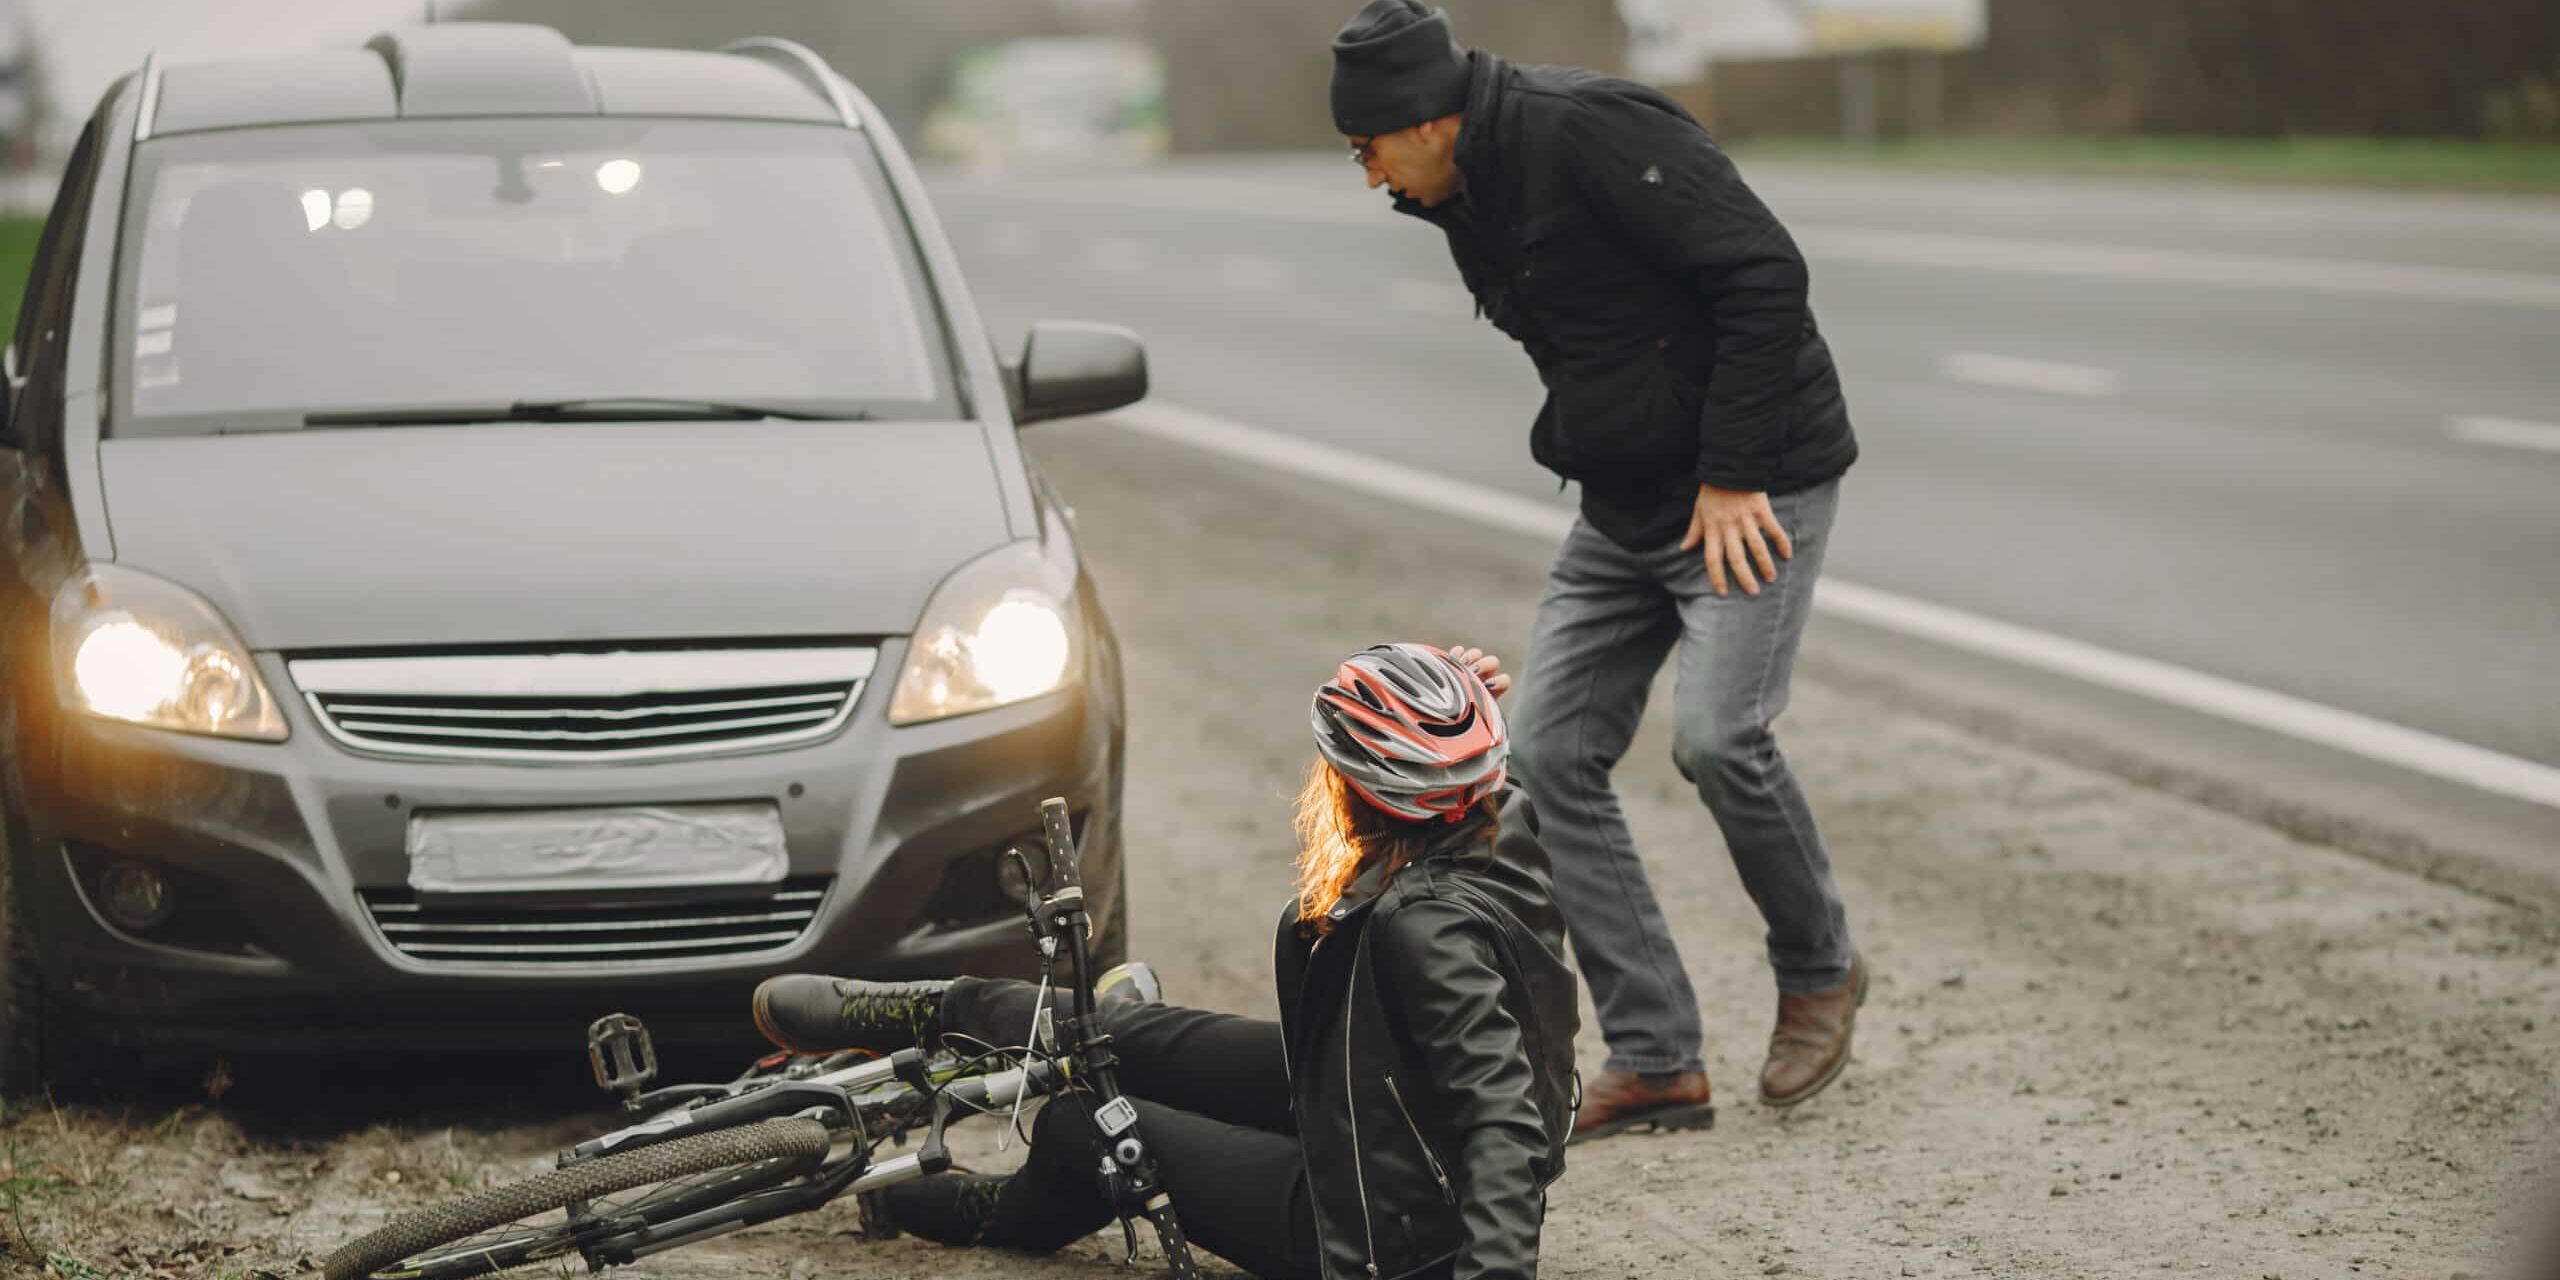
Navigating healthcare and financial protections after an auto accident in British Columbia requires understanding the province’s care-based system. Whether commuting through Vancouver traffic, driving across Burnaby, or navigating busy intersections near Oakridge, knowing how your medical recovery and wage protection are structured brings essential peace of mind.
In British Columbia, auto accident injuries are managed under the care-based no-fault model known as ICBC Enhanced Care. While this system provides broad medical treatments and wage replacement automatically for all BC residents, standard baseline benefits have specific caps and limitations—such as a $122,500 gross annual income threshold.
At Stratis Insurance, our independent advisors help high earners, business owners, and families evaluate their complete risk profile. By identifying potential coverage gaps and arranging private optional extensions like Income Top-Up protection and Extended Third-Party Liability, we empower you to protect your earnings and safeguard your family’s future.
What is ICBC Enhanced Care Coverage?
ICBC Enhanced Care is British Columbia’s care-based auto insurance model designed to prioritize medical recovery and financial stabilization following a motor vehicle collision. Under this framework, any BC resident injured in a crash, whether operating as a driver, riding as a passenger, walking as a pedestrian, or cycling, has immediate access to care benefits regardless of who caused the incident.
The care-based framework rests on three core pillars:
- Medical & Rehabilitation Recovery: Provides comprehensive medical treatment and rehabilitation support with no overall lifetime monetary limit for ongoing medical needs resulting from a crash.
- Income Replacement Benefit: Replaces 90% of your net income if injuries prevent you from working, calculated up to a maximum gross annual income cap of $122,500.
- Basic Vehicle Damage Coverage: Includes up to $200,000 in vehicle repair or replacement protection when another BC driver is at fault for the collision.
Pre-Approved Treatments: What Happens After a Crash?
Following an accident in British Columbia, accessing healthcare should be immediate and straightforward. Under ICBC Enhanced Care, injured individuals receive pre-approved access to essential medical and physical therapy treatments during the initial 12-week recovery window following the crash date.
During these initial 12 weeks, you can attend treatments directly using your ICBC claim number without an initial doctor’s referral or paying out-of-pocket expenses upfront:
- Physiotherapy: Initial assessment and physical rehabilitation sessions.
- Chiropractic Care: Spinal and musculoskeletal alignment treatments.
- Registered Massage Therapy (RMT): Soft tissue and muscle recovery therapies.
- Kinesiology: Active exercise rehabilitation and mobility restoration.
- Psychology & Counseling: Mental health support and trauma recovery care.
- Occupational Therapy: Workplace and daily living adaptation support.
If care is required beyond 12 weeks, your healthcare providers submit a registered care plan to ICBC to extend treatment funding for as long as medically necessary.
Personal Care & Auxiliary Benefits
For severe or catastrophic injury cases, Enhanced Care extends beyond medical treatments to support daily living requirements:
- Personal Care Assistance Allowance: Provides funding between $5,000 and $10,000 per month for severely injured individuals requiring assistance with daily activities like bathing or meal preparation.
- Caregiver Compensation: Offers up to $580 per week in financial support if an injured primary caregiver cannot perform household care duties for dependents.
- Permanent Impairment Compensation: Delivers a tax-free, single lump-sum payment to compensate for permanent physical or cognitive changes resulting from a crash.
ICBC Baseline vs. Stratis Private Extensions
While Enhanced Care delivers automatic baseline benefits, high earners and frequent travelers face financial exposure under standard caps.
| Coverage Category | ICBC Basic Enhanced Care | Private Optional Extensions (Through Stratis) |
| Medical Recovery | Pre-approved care for 12 weeks; lifetime ongoing care based on medical need. | Integrated health advisory and personalized portfolio coordination. |
| Wage Loss Replacement | 90% of net income capped at $122,500 gross annual earnings. | Private Income Top-Up policies protecting earnings up to $300,000+. |
| Third-Party Liability | $200,000 basic limit (lawsuits generally prohibited in BC). | Extended Liability ($2M to $5M+) for out-of-province & US travel claims. |
| Vehicle Damage Shield | Up to $200,000 basic coverage when another driver is at fault. | Private Collision & Comprehensive protection with customized deductibles. |
Closing the Income & Liability Gap
Relying solely on basic provincial coverage creates critical vulnerabilities for high-earning professionals, business owners, and cross-border commuters.
Income Top-Up Insurance for High Earners
The standard ICBC wage replacement formula covers 90% of net income up to a gross annual cap of $122,500. For professionals and business owners earning above this threshold, an accident could result in severe income loss. Private Income Top-Up insurance bridges this gap, securing your actual earning capacity (up to $300,000 or more) so mortgage payments, business expenses, and family commitments remain protected.
Real Client Scenario: Protecting True Earning Capacity
Consider a real-world scenario from the Lower Mainland: When a self-employed tech consultant in Vancouver was injured in an intersection collision, ICBC Enhanced Care immediately funded their physiotherapy sessions. However, because their annual income exceeded $180,000, the baseline ICBC wage replacement cap left a substantial monthly shortfall. Because they had reviewed their portfolio with Stratis beforehand, the Income Top-Up policy arranged through their advisor covered the earnings gap, ensuring their full financial capacity remained protected without missing a mortgage payment.
Extended Third-Party Liability (2M–5M+)
Under BC’s no-fault legislation, lawsuits for bodily injury resulting from crashes within British Columbia are restricted. However, when you drive your vehicle into other Canadian provinces or across the border into the United States, BC’s lawsuit restrictions do not protect you. If you cause a collision in Washington State or Alberta, you can be sued for millions in medical bills and property damage. Securing Extended Third-Party Liability through Stratis protects your personal wealth against out-of-jurisdiction legal claims.
Factors Impacting Total Policy Cost
While Stratis Insurance focuses purely on risk management and policy education rather than promotional pricing, understanding how policy elements are evaluated helps you structure your coverage effectively:
- Driving History & Experience: Your personal record of safe driving forms the primary baseline for risk tiering.
- Annual Mileage Usage Tiers: Vehicles driven lower distances annually (such as under 15,000 km per year) present less road exposure.
- Vehicle Usage Classification: Accurately rating whether your vehicle is used for pleasure, daily commuting, or commercial purposes ensures appropriate rate classing.
- Selected Deductibles & Add-Ons: Choosing higher deductibles on optional collision and comprehensive policies adjusts the balance between retained risk and private coverage.
Why Work with an Independent Broker for Enhanced Care Extensions?
Navigating government insurance guidelines can be complex. An independent advisor at Stratis Insurance evaluates your household income against provincial caps, identifies out-of-province liability risks, and cross-shops private insurance carriers to arrange tailored Income Top-Up and optional vehicle coverage. Furthermore, our advisors ensure your auto protection seamlessly complements your broader household assets, such as aligning policies under a comprehensive Home and Auto Insurance Bundling plan or exploring Private Auto Insurance Options.
Secure Your Full Protection Today
Ready to close coverage gaps and protect your true earning capacity? Contact an Advisor or Request a Quote at Stratis Insurance to review your ICBC Enhanced Care policy and private optional coverage choices today.
Educational Resource Note: For additional official details regarding care benefits and regulations, visit ICBC Enhanced Care Overview and the Insurance Bureau of Canada (IBC Pacific).
Frequently Asked Questions About ICBC Enhanced Care Coverage
What medical treatments are automatically pre-approved under ICBC Enhanced Care?
During the first 12 weeks following a crash, ICBC automatically pre-approves care sessions for physiotherapy, chiropractic care, registered massage therapy (RMT), kinesiology, psychology, and occupational therapy without requiring an initial doctor’s referral or upfront payment.
Can I sue another driver after a car accident in British Columbia?
Under BC’s Enhanced Care model, bodily injury lawsuits against other BC drivers for crashes occurring within the province are generally prohibited. Instead, all injured parties receive medical care and wage benefits directly from ICBC regardless of fault. However, exceptions exist for crashes involving out-of-province drivers or commercial entities convicted of specific criminal offences.
How much wage replacement does ICBC pay if I am injured and cannot work?
ICBC Enhanced Care pays an Income Replacement Benefit that covers 90% of your net income, calculated up to a maximum gross annual income cap of $122,500. Payments begin on the eighth day following the crash and continue bi-weekly throughout your recovery.
What happens if my annual income is higher than the $122,500 ICBC limit?
If your annual earnings exceed $122,500 gross, standard ICBC benefits will not replace income above that cap. To protect your full earnings, you can purchase private Income Top-Up insurance through an independent broker like Stratis to cover earnings up to $300,000 or more.
Why do I still need private optional insurance if Enhanced Care is automatic?
While Enhanced Care provides automatic medical benefits in BC, it does not cover Extended Third-Party Liability for out-of-province travel (e.g., US trips), full wage protection for earnings over $122,500, or optional physical vehicle damage (collision and comprehensive) with customized deductibles.
Can I get a private car insurance quote in Vancouver instead of buying optional ICBC coverage?
Yes. While mandatory Basic Autoplan must be purchased through ICBC, you maintain full freedom to obtain optional collision, comprehensive, and extended liability coverage through private insurance carriers via Stratis.
How can I optimize my overall car insurance policy in Vancouver?
You can optimize your policy by reviewing your annual mileage tier, ensuring your vehicle usage classification is accurate, matching deductibles to your emergency budget, and consulting a broker to evaluate private income top-up choices.
Does my Vancouver car insurance policy cover me when driving into the United States?
Personal BC auto policies generally extend coverage into the US. However, because US laws allow bodily injury lawsuits, carrying Extended Third-Party Liability ($2M to $5M) through a private insurer is strongly recommended prior to traveling.
What information do I need to prepare to get an accurate quote?
To evaluate your coverage needs, prepare your current ICBC Autoplan renewal document, driver’s license details, proof of annual income (if evaluating Income Top-Up options), and details regarding your primary driving usage.
Like the article? Share it with your friends!